

The current year depreciation is the portion of a fixed asset’s cost that we deduct against current year profit and loss. The accounting concept behind depreciation is that an asset produces revenue over an estimated number of years; therefore, the cost of the asset should be deducted over those same estimated years. However, note that eventually, we must switch from using the double declining method of depreciation in order for the salvage value assumption to be met. Since we’re multiplying by a fixed rate, there will continuously be some residual value left over, irrespective of how much time passes. Certain fixed assets are most useful during their initial years and then wane in productivity over time, so the asset’s utility is consumed at a more rapid rate during the earlier phases of its useful life. At the beginning of the first year, the fixture’s book value is $100,000 since the fixtures have not yet had any depreciation.
Salvage Value and Book Value: How Double Declining Balance Depreciation Method Works

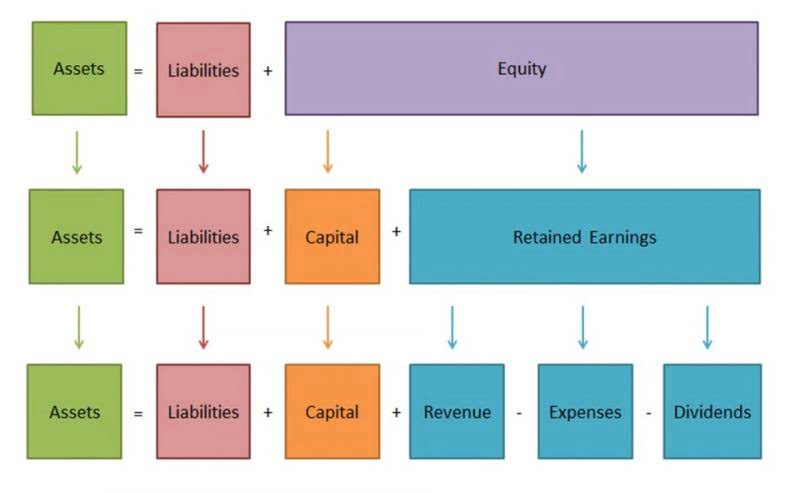
In that year, the depreciation amount will be the difference between the asset’s book value at the beginning of the year and its final salvage value (usually a small remainder). Salvage value is the estimated resale value of an asset at the end of its useful life. Book value is the original cost of the asset minus accumulated depreciation.
Why Is Double Declining Depreciation an Accelerated Method?
Depreciation is how an asset’s book value is “used up” as it helps to generate revenue. In the case of the semi-trailer, such uses could be delivering goods to customers or transporting goods between recording transactions warehouses and the manufacturing facility or retail outlets. All of these uses contribute to the revenue those goods generate when they are sold, so it makes sense that the trailer’s value is charged a bit at a time against that revenue. There are always assumptions built into many of the items on these statements that, if changed, can have greater or lesser effects on the company’s bottom line and/or apparent health. Assumptions in depreciation can impact the value of long-term assets and this can affect short-term earnings results. Assume that you’ve purchased a $100,000 asset that will be worth $10,000 at the end of its useful life.

Filing Taxes Late: Everything Business Owners Need to Know
In the second year, depreciation is calculated in a regular way by multiplying the remaining book value of $36,000 ($40,000 — $4,000) by 40%. For example, if the equipment in the above case is purchased on 1 October rather than 2 January, depreciation for the period between 1 October and 31 December is ($16,000 x 3/12). This is when that year’s depreciation is limited to the amount that will reduce the asset’s book value to its residual value. Because the book value declines as the asset ages and the rate stays constant, the depreciation charge falls each year. Suppose that trailer technology has changed significantly over the past three years and the company wants to upgrade its trailer to the improved version while selling its old one.
- The double declining balance method is considered accelerated because it recognizes higher depreciation expense in the early years of an asset’s life.
- By mastering these adjustments, I can better manage my assets and their depreciation, ensuring that my financial statements reflect the true value of my investments.
- But you can reduce that tax obligation by writing off more of the asset early on.
- To calculate it, you take the asset’s starting value, find its useful life, and then multiply the starting value by double the straight-line rate.
Depreciation is the act of writing off an asset’s value over its expected double declining balance method useful life, and reporting it on IRS Form 4562. The double declining balance method of depreciation is just one way of doing that. Double declining balance is sometimes also called the accelerated depreciation method. Businesses use accelerated methods when having assets that are more productive in their early years such as vehicles or other assets that lose their value quickly.
- In year 5, companies often switch to straight-line depreciation and debit Depreciation Expense and credit Accumulated Depreciation for $6,827 ($40,960/6 years) in each of the six remaining years.
- However, in the units-of-activity method (and in the similar units-of-production method), an asset’s estimated useful life is expressed in units of output.
- Through this example, we can see how the DDB method allocates a larger depreciation expense in the early years and gradually reduces it over the asset’s useful life.
- This is just one example of how a change in depreciation can affect both the bottom line and the balance sheet.
- Assume that you’ve purchased a $100,000 asset that will be worth $10,000 at the end of its useful life.
- An asset for a business cost $1,750,000, will have a life of 10 years and the salvage value at the end of 10 years will be $10,000.
- However, the depreciation will stop when the asset’s book value is equal to the estimated salvage value.
- Under the generally accepted accounting principles (GAAP) for public companies, expenses are recorded in the same period as the revenue that is earned as a result of those expenses.
- In many countries, the Double Declining Balance Method is accepted for tax purposes.
- Save more by mixing and matching the bookkeeping, tax, and advisory services you need.
- In case of any confusion, you can refer to the step by step explanation of the process below.
- All information prepared on this site is for informational purposes only, and should not be relied on for legal, tax or accounting advice.
If the double-declining depreciation rate is 40%, the straight-line rate of depreciation shall be its half, i.e., 20%. Double-declining depreciation charges lesser depreciation in the later years of an asset’s life. To calculate the double-declining depreciation expense for Sara, we first need to figure out the depreciation rate. In the last year of an asset’s useful life, we make the asset’s net book value equal to its salvage or residual value. This is to ensure that we do not depreciate an asset below the amount https://www.bookstime.com/ we can recover by selling it.
- With the constant double depreciation rate and a successively lower depreciation base, charges calculated with this method continually drop.
- A common mistake is forgetting to adjust the final year’s depreciation to not drop below the salvage value.
- In the following accounting years, the 20% is multiplied times the asset’s book value at the beginning of the accounting year.
- Depreciation is the act of writing off an asset’s value over its expected useful life, and reporting it on IRS Form 4562.
- However, the amount of depreciation expense in any year depends on the number of images.
- Over the depreciation process, the double depreciation rate remains constant and is applied to the reducing book value each depreciation period.
SYD is An Accelerated Method of Depreciation
This not only provides a better match of expense to the car’s usage but also offers potential tax benefits by reducing taxable income more significantly in those initial years. Every year you write off part of a depreciable asset using double declining balance, you subtract the amount you wrote off from the asset’s book value on your balance sheet. Starting off, your book value will be the cost of the asset—what you paid for the asset. Of course, the pace at which the depreciation expense is recognized under accelerated depreciation methods declines over time.